Hurricane Season Prep Checklist for Cape Coral Homeowners
A room-by-room, week-by-week checklist for getting a Cape Coral home ready before a storm, not during one.
Wind damage is usually covered. Storm surge and flooding usually are not. Here is what a standard Florida homeowners policy actually pays for.
Most Florida homeowners policies cover wind damage from named storms and hurricanes as a standard peril, the same way they cover damage from any other windstorm. That includes a roof torn open by wind, siding ripped off, a window broken by flying debris, and the water damage that follows once wind creates an opening for rain to get in.
This is the most common source of confusion: if wind damaged your roof and rain then got inside through that opening, the resulting interior water damage is typically covered as part of the same wind claim, because the wind event caused it.
A standard homeowners policy does not cover storm surge or rising floodwater, even during the same hurricane that caused wind damage. If water comes up from the ground, a canal, or the street rather than down through a wind-created opening, that is flood damage, and it requires a separate flood insurance policy.
This single distinction, wind-driven water versus rising floodwater, decides which policy pays and is the single biggest source of denied or underpaid storm claims in Florida.
The source of the water, not how much damage it caused, is what determines coverage.
| Scenario | Usually Classified As | Typically Covered By |
|---|---|---|
| Wind tears off roof shingles, rain gets in | Wind damage | Standard homeowners policy |
| Storm surge pushes water into the garage | Flood damage | Separate flood insurance policy |
| Canal rises and floods the lanai | Flood damage | Separate flood insurance policy |
| Window breaks from wind-blown debris, rain enters | Wind damage | Standard homeowners policy |
| Heavy rain backs up through a clogged storm drain | Often classified as flood | Separate flood insurance policy (varies by cause) |
Florida policies typically carry a separate, higher deductible specifically for named storms and hurricanes, usually written as a percentage of the home’s insured value rather than a flat dollar amount. A 2 percent hurricane deductible on a $400,000 insured home works out to $8,000 before the policy pays anything, which is often far more than the standard deductible that applies to non-storm damage.
Check your declarations page before a storm season starts, not after a claim, so the deductible is not a surprise on top of the damage itself.
Photos and video of your home’s condition before a storm, roof, siding, fencing, give you something to compare against afterward, which speeds up every claim that follows. After a storm, photograph everything before any cleanup starts, including the source of the damage if you can safely identify it, wind-torn shingles versus a waterline on a wall, for example.
Keep every receipt for emergency repairs, since reasonable costs to prevent further damage, like a roof tarp, are typically reimbursable as part of the claim.
We document damage the way adjusters expect to see it.
A common reason wind claims get underpaid is an adjuster attributing damage to flooding instead of wind, or to pre-existing wear instead of the storm, without a clear record to contradict it. Detailed photo documentation, moisture readings, and a written scope of damage from a restoration crew can support an appeal.
You generally have the right to request a second inspection or hire a public adjuster if you believe a settlement does not reflect the actual damage. Our Insurance Claims Help page walks through that process in more detail.
Already have storm damage and need the repair and documentation handled by one crew? See our Storm Damage Restoration service in Cape Coral.
Wind damage from a hurricane is typically covered under a standard policy. Storm surge and flooding during the same hurricane usually require separate flood insurance.
A separate, usually higher deductible that applies specifically to named storm damage, typically written as a percentage of the home’s insured value rather than a flat dollar amount.
Rarely. Standard homeowners policies exclude flood damage almost universally. Flood coverage requires a separate policy, often through the National Flood Insurance Program or a private flood insurer.
Every affected area before any cleanup begins, the apparent source of the damage, and anything that shows whether the damage came from wind versus rising water.
Yes. You can request a re-inspection, submit additional documentation, or involve a public adjuster. A clear, dated record of the damage makes a dispute far more likely to succeed.
Roof damage, water intrusion, and claim documentation handled by one crew, anywhere in Cape Coral.
A room-by-room, week-by-week checklist for getting a Cape Coral home ready before a storm, not during one.
Read article →
A step-by-step walkthrough of filing a storm damage claim in Florida, from the first call to getting repairs approved.
Read article →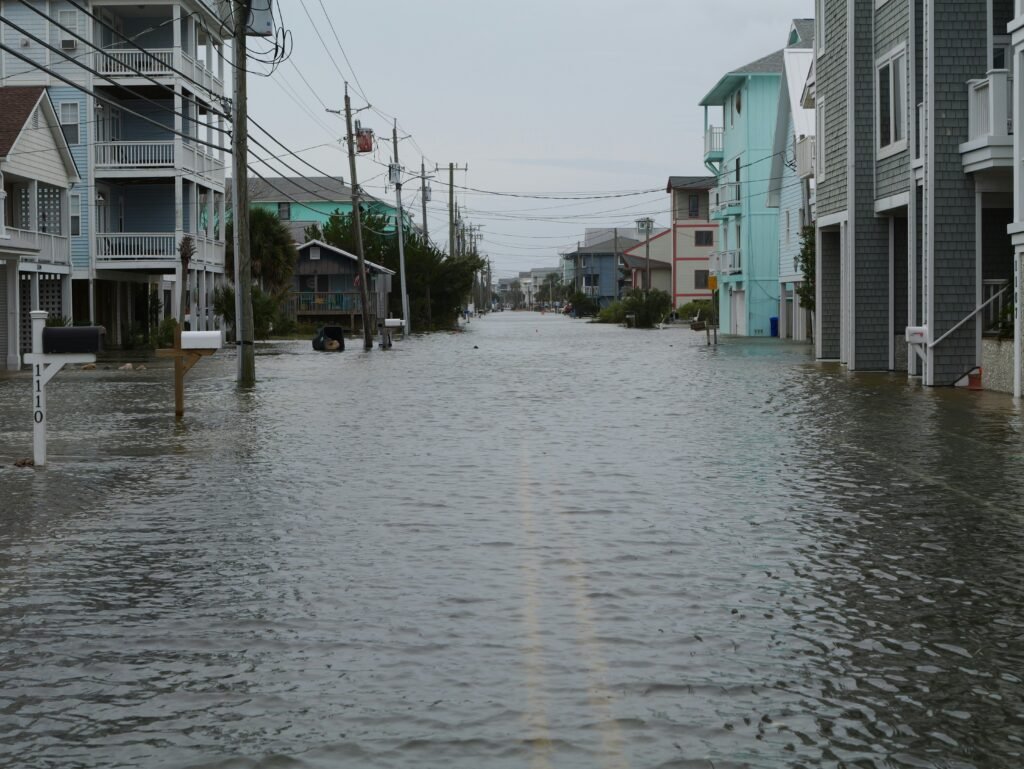
Two homes with the same amount of water damage can have completely different insurance outcomes. The difference comes down to where the water came...
Read article →